
What’s the Best Way to Tackle Debt: Snowball or Avalanche Method?
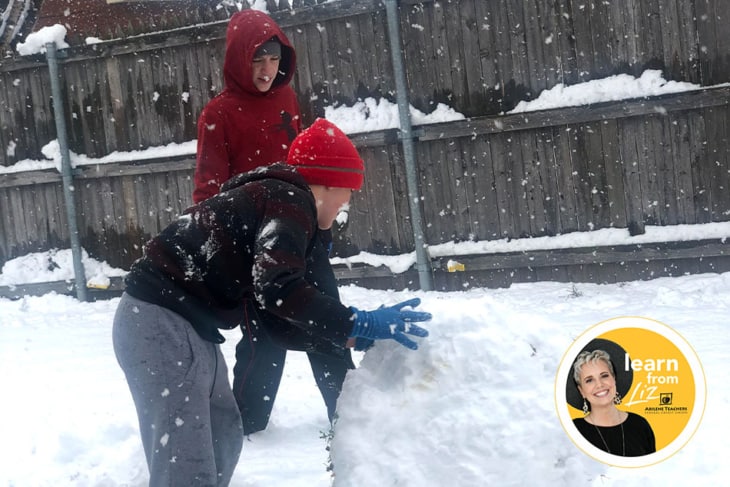
That photo above is a favorite memory of my sons rolling a massive snowball. It felt like it took them no time at all to go from a tiny, baseball-sized handful of packed snow to that giant boulder of a base.
If only paying off consumer debt was that quick and easy! While clearing away your balances certainly takes a bit longer than building a real snowball, the end result of living a completely debt-free life is worth every ounce of time and effort you pour into it.
Debt is the ultimate financial killjoy. It destroys your monthly cash flow, makes long-term lifestyle planning feel impossible, and shadows every single purchase you make with an underlying sense of guilt. Nobody wants to live under that kind of weight. But how do you actually kiss your balances goodbye for good?
Crawling out from under a mountain of bills takes real intent, but if you are ready to realign your priorities, you can shake off debt no matter how large the balance is. Let’s explore the two most popular strategic approaches to debt payoff:
Strategy 1: The Debt Snowball Method
Popularized by financial authors, the Debt Snowball focuses entirely on human psychology and behavioral modification rather than pure math. It involves listing your debts from the smallest balance to the largest balance, regardless of the interest rates.
How It Works in Practice
Imagine you have audited your budget and squeezed out an extra $500 a month to channel aggressively toward your debt payoff. Here is your baseline scenario:
- Personal Loan: $2,500 balance at 9.5% interest –} Minimum Payment: $50
- Auto Loan: $10,000 balance at 3.0% interest –} Minimum Payment: $200
- Credit Card Debt: $13,000 balance at 18.99% interest –} Minimum Payment: $225
- Student Loan: $18,000 balance at 4.5% interest –} Minimum Payment: $300
Using the Snowball method, you place all your bills on automatic minimum payments except for the smallest one (the Personal Loan). You pour your extra $500 into that loan, paying a total of $550 a month until it reads zero.
Once that personal loan is wiped out, you take that entire $550 sum and roll it directly into the next-smallest bill: the Auto Loan. Now, you are striking that car payment with $750 a month ($550 rolled over + the $200 regular minimum). Once the car is paid off, you roll that combined $750 into the credit card, creating a massive financial snowball that knocks out your remaining liabilities faster and faster.
- The Pros: It thrives on momentum. Reaching a zero balance quickly provides an immediate psychological win, triggering a sense of accomplishment. In fact, a study published by the Harvard Business Review proved that starting your journey with your smallest balance is often the single most effective way to keep your motivation high enough to finish the job. As the old saying goes, personal finance is 20% head knowledge and 80% behavior.
- The Cons: It is completely indifferent to interest rates. By targeting the smallest balance first, you might hold onto a massive, high-interest retail card much longer, which can cost you extra money in cumulative interest fees over time.
Strategy 2: The Debt Avalanche Method
The Debt Avalanche takes a mathematical approach. Instead of looking at the size of the balance, you list your debts in strict order from the highest interest rate down to the lowest interest rate.
How It Works in Practice
Using the exact same financial numbers from our example above, the Avalanche method ignores the small personal loan balance and targets the Credit Card Debt first, because its 18.99% interest rate is draining the most money from your wallet every month.
You would pay the minimum amounts on the other three loans and channel your entire extra $500 into the credit card account ($725 total monthly payment) until it is completely crushed. From there, you would move to the next-highest rate: the Personal Loan (9.5%), followed by the Student Loan (4.5%), and finally the Auto Loan (3.0%).
- The Pros: It is the most financially efficient method. Wiping out your highest interest rates first shields your money from compound fees, saving you hundreds—or even thousands—of dollars in overall interest. Because you are preventing those steep monthly interest drains early, the Avalanche path often results in becoming debt-free slightly faster.
- The Cons: It requires intense mental discipline. If your highest-rate debt also happens to be a massive balance, it can take months or even years of aggressive payments before you see your very first account read “zero.” Without those quick psychological wins, it can be easier to lose steam and quit before making a major dent.
Which Path is Right for You?
Choosing a strategy comes entirely down to your unique personality and lifestyle.
- If you know you need early, fast victories to stay excited and committed to a plan, the Debt Snowball is your perfect match.
- If your primary goal is outsmarting the math and saving the absolute maximum amount of cash on interest fees, the Debt Avalanche is your winner.
Remember, there is no rule saying you can’t switch paths or create a hybrid strategy down the line! The most critical step is simply getting started.
Ready to audit your balances? Log into your ATFCU digital banking dashboard and open our built-in Money Management tool. It securely pools all your accounts in one clear visual map, allowing you to track your liabilities, set automated milestones, and watch your debt footprint shrink in real time. Pick your strategy today, and let’s roll toward financial freedom together!